
EYES ONLY
SUBSCRIBER ONLY // DO NOT FORWARD WITHOUT PERMISSION
BLACKOPS
FINANCE
FINANCE
COVERT FINANCIAL INTELLIGENCE. INTERCEPTED DAILY.
5 October 2026
DAILY DOSSIER
MISSION BRIEF
Updated 1115 ET
The route that has kept the oil market from breaking was hit again this weekend. By Monday morning there were two accounts of what happened to it.
On Sunday the Houthis claimed missile and drone strikes on Saudi Aramco sites in Riyadh and the Khurais area. An energy sector source in Saudi Arabia told AFP that a pumping station on the East-West pipeline at Khurais, east of Riyadh, had been hit for the first time, that the damage was big, and that the pipeline had stopped again.
People familiar with the matter told Bloomberg the opposite: crude is still moving through the line as normal. Reuters is reported to have carried the same. The Saudi-led coalition in Yemen called the Houthi claim misleading. As of this morning, Saudi Aramco and the energy ministry had not answered Bloomberg’s request for comment. Both accounts rest on unnamed sources. Neither is official, and this letter does not attribute the attack to anyone.
Brent rose about 1.2% on the first reports and gave the gain back once the Bloomberg report landed. It touched $103.06 in early Asian trading and was quoted at $101.75, down about 0.5%, this morning. Those are intraday marks and they will move.
Why one pumping station can move a global price. The East-West line runs about 1,200 kilometres from the eastern fields to Yanbu on the Red Sea. With the Strait of Hormuz constricted, it is the main way Saudi crude reaches open water without passing Iran. Bloomberg reported on Friday that Aramco had raised flows to more than 80% of the line’s 7 million barrels a day of capacity, about 6 million, leaving roughly 4.5 million a day for export after the Red Sea refineries take their share. Friday’s letter could not verify a rate; this one rests on a single outlet.
Aramco’s chief executive, Amin Nasser, put a number on the pipeline this morning in London. Without it, he said, Brent could have reached $200 a barrel. He called global stockpiles “scarily thin”, said emergency releases offer only temporary relief, and warned that the market could take up to two years to recover after Hormuz fully reopens. That is the operator of the asset describing it as the thing standing between the market and a price roughly twice today’s. Hold that next to a Brent price that moved about a dollar on a report that the asset had stopped.
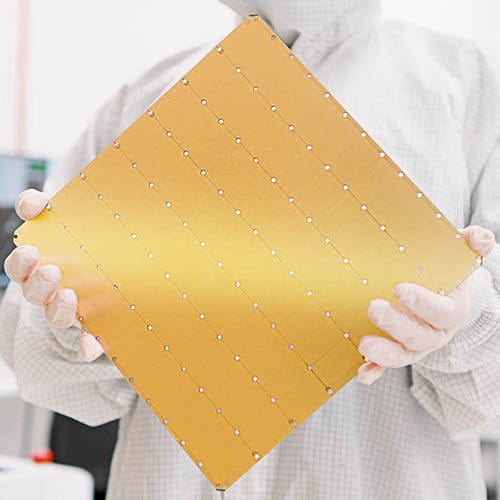
Its “golden tablet” can produce intelligence up to 1,000 times FASTER than regular AI.
And Jeff believes by November 11…
Elon Musk is going to accelerate the demand for this company’s patented technology…
Sending shares higher than anyone can imagine. Click here to see the details.
THE OPERATION
The bypass has two ends, and both were under fire this weekend
The pipeline is only half the bypass. Crude loaded at Yanbu still has to leave the Red Sea, and for cargoes bound for Asia that means the Bab el-Mandeb strait at its southern mouth.
That exit now sits inside a war. A truce in Yemen that had held since 2022 collapsed in July. In mid-September the Houthis took the port of Mocha and islands in the strait. On Sunday the internationally recognised government announced operations to retake territory including the capital, Sanaa, with the Saudi-led coalition pledging support. Its military says it has retaken the strait; Houthi media deny it. Neither claim can be verified from here, and this letter does not say who controls the waterway.
Shipping already reflected the risk. Traffic through the Bab el-Mandeb was reported at about 30 vessels a day in late September, against a normal 80. War-risk insurance for Saudi-linked tankers loading at Yanbu was reported to have tripled, to about 3% of a vessel’s value. The alternative is the long way round Africa, which one report estimates adds about a month to deliveries into Asia.
The other side of the ledger is real too. Reuters ship-tracking data shows Middle East crude exports above their pre-war baseline on four of seven days in late September, at between 19.5 and 22.5 million barrels a day, against a baseline of 18 million. The seven-day average stood at 18.5 million on 1 October. JPMorgan puts shipments at 98% of pre-war levels.
Riyadh has priced for that recovery, not for the weekend. Aramco cut its November official selling price for Arab Light to Asia to a $5 discount to the regional benchmark, from $2, the widest in six years. Traders had expected an increase. A producer cutting its price to win customers back is a producer that expects to have barrels to sell.
Volumes are up and so are incidents. The same Reuters report counts at least seven tanker incidents in the Hormuz region, including a crude carrier struck by an unknown projectile on 1 October. UK Maritime Trade Operations has recorded at least one attack a day since 2 October. This morning a tanker turned back in the strait after a warning from Iran’s Revolutionary Guard.
A meaningful share of the recovery in Gulf exports depends on routes that avoid Hormuz, and the largest of them runs overland to a sea whose southern mouth is being fought over. The market’s verdict, expressed in a Brent price near $102 and a Saudi price cut to Asia, is that the bypass holds. That may well be right. But it is a verdict reached on unnamed sources on both sides, before the operator has said anything, and with stockpiles its own chief calls scarily thin. Nobody outside Aramco knows this morning what is flowing through Khurais.
RULES OF ENGAGEMENT
What moved after Friday, and a week that runs through the fuel bill
Two things in Friday’s letter moved after it went out, and both need saying. The European diesel release it described as under discussion was agreed that afternoon. The G7 will release up to 100 million barrels of crude and diesel over four months, with a substantial diesel release front-loaded into the first twenty days. The split between diesel and crude, and the shares by country, were not disclosed.
And the bond rally did not last. Friday’s letter said the bond market read the jobs report as weakness, with the ten-year at 5.16% that morning. By the close it was 5.28%, higher on the day. This morning it is quoted between 5.25% and 5.30% depending on the screen, and the thirty-year near 5.66%. Hiring at 29,000 a month alongside long yields described as the highest since 2002 is not a pairing the textbook expects. Which gives first is not known.
Stocks took the jobs report better than bonds did. The S&P 500 closed Friday at 7,722.72, up 0.73%, and futures were slightly softer before Monday’s open. Gold is $4,150.60, up 0.25% on the day and down 5.8% on the month. The dollar index touched 102.53 overnight, near an eighteen-month high, and was around 102.20 in European trading. All intraday.
Money markets have taken October off the table. Pricing for an increase on 28 October is around 20%, from about 70% a week earlier. One source puts the odds of a December increase near 69%; another puts the odds of a hike by year end at 84%. Both are printed because they do not agree.
The calendar. Minutes of the September meeting, which raised rates, are published on Wednesday. Vice Chair Michelle Bowman speaks on regulation on Tuesday; Governor Christopher Waller speaks on the economic outlook on Thursday. September consumer prices arrive on 14 October. In August headline inflation was 3.4% while the core measure, which strips out food and energy, was 2.4%. Energy was up 16.3% on the year and gasoline 27.4%. That gap is the fuel, measured.
On the strait itself, the diplomacy did not move. Iran’s parliament speaker said on Sunday that Hormuz would not open until seven conditions were met, and Tehran says it is reviewing a United States response. No reopening date exists, and none is offered here.
The exposure today is not the attack. It is the confidence with which the market has decided the attack did not matter. Monday’s round trip in Brent was a judgment between two anonymous sources, made before Aramco or the energy ministry had said a word. If the calmer account holds, little has changed. If the AFP account holds, the line that Aramco’s own chief says kept Brent from $200 is down again while the sea it empties into is being fought over and stockpiles are, in his words, scarily thin. The G7 release is finite: 100 million barrels is roughly five or six days of Middle East crude exports, spread across four months. Watch for the first official statement on Khurais and the first loading data out of Yanbu. Until one arrives, a Brent price near $102 is a bet on a sentence, not a measurement.
Editorial sources: AFP, as carried by L’Orient Today and The Business Standard, 5 October 2026, for a Saudi energy sector source stating that the East-West pipeline was attacked on 4 October at a previously untargeted pumping station at Khurais east of Riyadh, that the damage was big and that the pipeline stopped again, and for Kpler data dating the previous halt to 11 to 22 September; Bloomberg, 5 October 2026, as reported by Arab Times and ZeroHedge, for people familiar with the matter saying crude continues to flow through the pipeline as normal, for Saudi Aramco and the energy ministry not immediately responding to requests for comment, and for Brent rising about 1.2% on the attack reports before declining; CBS News live coverage, 5 October 2026, for Reuters and Bloomberg reporting oil still flowing normally, for the Yemeni military claiming to have retaken the Bab el-Mandeb strait and Houthi media denying it, and for a tanker turning back in the Strait of Hormuz after a Revolutionary Guard warning, confirmed by UK Maritime Trade Operations; Al Jazeera, 4 October 2026, for the Houthi claim by spokesman Yahya Saree of ballistic missile and drone strikes on Aramco in Riyadh, for coalition spokesman Turki al-Maliki calling the claim misleading, for the collapse in July 2026 of the 2022 truce, and for the Houthi seizure of Mocha port and islands in the Bab al-Mandeb strait in mid-September; The Nation (Thailand), 5 October 2026, for the Houthi claim naming Aramco sites in Riyadh and the Khurais area, and for Brent at $103.06 up 0.79% in early trading; OilPrice.com, 5 October 2026, for the internationally recognised Yemeni government announcing operations on 4 October to reclaim Houthi-held territory, and for the estimate that rerouting around the Cape of Good Hope adds about a month to Asian deliveries; CNN, 4 October 2026, for the Saudi-led coalition pledging support for the Yemeni offensive; OilPrice.com, 25 September 2026, for Bab al-Mandab traffic of about 30 vessels a day against a normal 80, and for war-risk insurance on Saudi-linked tankers at Yanbu tripling to about 3% of vessel value; Bloomberg, 2 October 2026, as carried by Investing.com, for East-West pipeline flows above 80% of 7 million barrels a day of capacity, about 6 million barrels a day, with roughly 4.5 million barrels a day available for export; The Business Standard (AFP), 5 October 2026, for the pipeline length of about 1,200 kilometres; The National, 5 October 2026, for Amin Nasser’s remarks at the Energy Intelligence Forum in London that Brent could have reached $200 without the East-West pipeline, that global stockpiles are scarily thin, that emergency releases offer temporary relief, and that market recovery could take up to two years after Hormuz reopens; Reuters (Florence Tan), 4 to 5 October 2026, as carried by U.S. News and Galveston County Daily News, for Middle East crude exports above the pre-war baseline on four of seven days in late September at 19.5 to 22.5 million barrels a day against an 18 million barrel baseline for March 2025 to February 2026, for a seven-day average of 18.5 million barrels a day on 1 October, for at least seven tanker incidents in the Hormuz region including the Kazimah III on 1 October, and for UK Maritime Trade Operations recording at least one attack daily since 2 October; The National, 5 October 2026, for the November Arab Light official selling price to Asia at a $5 discount against $2 in October, the lowest in six years, against expectations of an increase, and for JPMorgan’s estimate of shipments at 98% of pre-war levels; Trading Economics, Brent Crude Oil, 5 October 2026, for Brent at $101.75 down 0.49%; Yahoo Finance live coverage, 2 October 2026, and Bloomberg and BNN Bloomberg, 2 October 2026, for the G7 agreement to release up to 100 million barrels of crude and diesel over four months with a front-loaded diesel release within twenty days, announced by the French presidency of the G7, with the diesel-crude split and country breakdown undisclosed; Yahoo Finance market close, 2 October 2026, and Charles Schwab market update of 5 October 2026 at 9:11 a.m. Eastern, for the S&P 500 close of 7,722.72 up 0.73% and the ten-year Treasury yield at 5.28%; Trading Economics, United States Government Bond Yields and 30-Year Bond Yield, 5 October 2026, for the ten-year at 5.30% with narrative text placing it near 5.25%, and the thirty-year at 5.66%, and for the characterisation of the ten-year as near its highest since 2002; Benzinga via TradingView, 5 October 2026, for the ten-year at 5.25%, index futures lower and October rate-increase pricing of 20.5%; Trading Economics, Gold, 5 October 2026, for gold at $4,150.60 up 0.25% and down 5.77% on the month, and for roughly 80% pricing of no change in October and about 69% for a December increase; Charles Schwab, 5 October 2026, for October rate-increase odds of about 20% against 70% the previous week and year-end increase odds of 84%; FXStreet, 5 October 2026 at 09:24 GMT, for the dollar index near 102.20 after a 102.53 high, near eighteen-month highs; Board of Governors of the Federal Reserve System, October 2026 calendar (primary), for Vice Chair Bowman on 6 October and Governor Waller on the economic outlook on 8 October; Yardeni QuickTakes, FXStreet and Charles Schwab weekly previews, for publication of the September FOMC minutes on 7 October; U.S. Bureau of Labor Statistics, CPI home page (primary), for the September 2026 CPI release on 14 October 2026 at 8:30 a.m. Eastern; U.S. Bureau of Labor Statistics, Consumer Price Index for August 2026, USDL-26-1496, released 11 September 2026 (primary), for headline CPI up 3.4% and core CPI up 2.4% over twelve months, energy up 16.3% and gasoline up 27.4%; Al Jazeera, 4 October 2026, for parliament speaker Mohammad Bagher Ghalibaf stating that the strait will not open until seven conditions are met; CBS News live coverage, 5 October 2026, for Iranian officials reviewing the United States response and preparing a counterproposal; BlackOps Finance edition of 2 October 2026, for the ten-year at 5.16% intraday and the description of the European diesel release as under discussion.
END OF TRANSMISSION.
EYES ONLY
EYES ONLY
SUBSCRIBER ONLY // DO NOT FORWARD WITHOUT PERMISSION