
EYES ONLY
SUBSCRIBER ONLY // DO NOT FORWARD WITHOUT PERMISSION
BLACKOPS
FINANCE
FINANCE
COVERT FINANCIAL INTELLIGENCE. INTERCEPTED DAILY.
28 September 2026
DAILY DOSSIER
MISSION BRIEF
Updated 1115 ET
The war in the Gulf acquired a price on Saturday. Iran put an offer on the table and the President of the United States turned it down in public, and this morning the oil market repriced what that refusal is worth.
The terms, as reported, were these. Iran’s foreign minister Abbas Araghchi offered to reopen the Strait of Hormuz and return to negotiations on the nuclear programme within seven days. In exchange the United States would withdraw its military strikes, lift the naval blockade on Iranian ports, lift sanctions and release frozen Iranian assets.
The answer was no. “They made a proposal but I rejected it,” the President said. He added that Iran had “outsmarted themselves” by closing the strait in the first place, and that “I came along, and we put up the greatest blockade ever in military history.”
Oil opened accordingly. Brent for November was quoted at $108.48 a barrel at 6:35 Eastern this morning, up about 4%. West Texas Intermediate was at $96.16, up about the same. Both figures are intraday and both will be different by the close. Friday had gone the other way: Brent fell 2.1% on the reports that a phased reopening was being explored.
The Treasury market took it as an inflation event rather than a risk event. The ten-year note is around 5.22% this morning, described as its highest since July 2007, on strengthening expectations that the Federal Reserve will tighten further to contain inflation. The thirty-year is at 5.52%, the five-year at 5.05% and the two-year at 4.90%. Nothing rallied.
And on Friday afternoon the households filed their report. The University of Michigan’s final September survey put sentiment at 48.1, down 7.0% from August’s 51.7 and the lowest in four months. Year-ahead inflation expectations rose to 4.6% from 4.0%. The long-run measure rose to 3.4% after three consecutive months at 3.3%. Joanne Hsu, who runs the survey, reported that views of current and year-ahead personal finances each weakened about 10% on the month, “with concerns over high prices continuing to climb.”
An energy shock is the one inflation a central bank cannot do anything about, and it is also the one it cannot ignore. Raising the federal funds rate does not produce a barrel of oil and does not reopen a shipping lane. What a rate rise can do is compress demand until the price of everything else falls far enough to make room for the fuel bill, which is a slower and more painful mechanism than the phrase “fighting inflation” suggests. So why move at all? Because of the second number in the Michigan release. A committee can tolerate a price shock it did not cause. What it cannot tolerate is households revising up what they expect prices to do next, because expectations are the part of inflation that becomes self-fulfilling through wages and contracts. Year-ahead expectations went from 4.0% to 4.6% and the long-run measure broke a three-month plateau. That is the number the Federal Reserve is defending, and it is the reason a hiking cycle continues into an economy whose consumers rate it at 48.1.
SPONSORED
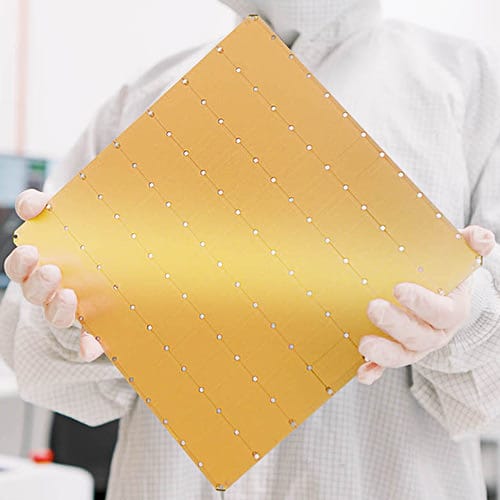
Its “golden tablet” can produce intelligence up to 1,000 times FASTER than regular AI.
And Jeff believes by November 11…
Elon Musk is going to accelerate the demand for this company’s patented technology…
Sending shares higher than anyone can imagine. Click here to see the details.
THE OPERATION
The strait is not closed
Now take the framing apart, because the phrase everyone is using this morning is wrong in a specific and checkable way. The Strait of Hormuz is not closed.
Two independent accounts of the shipping data agree on the same pair of figures. There were roughly 132 ship passages through the strait between 21 and 27 September. The pre-war norm was approximately 130 crossings a day. Set one against the other – and that comparison is our arithmetic, not a sourced statistic – and last week ran at something close to a seventh of one normal day’s traffic, spread over seven days. That is a near-total constriction. It is not a closure, and the difference matters, because traffic that exists can be scaled up by agreement in a way that traffic which has been physically stopped cannot.
No barrel volume is printed in this edition. Two sources gave figures that cannot both be true: one put roughly forty million barrels through the strait in a recent forty-eight hours, another put 33.7 million barrels across a full week. Those differ by a factor of about seven and no third source could settle it, so neither appears above. The passage count does appear, because two accounts give it identically.
Hold that against the price action, because together they tell you what this morning actually was. The physical situation on Friday and the physical situation today are the same situation. Nothing was loaded or unloaded, no tanker was sunk, no new lane was blocked. Brent fell 2.1% on Friday because a deal looked closer and rose about 4% today because it looked further away. What moved was the risk premium, which is the market’s estimate of the probability of a future disruption, not a measurement of a present one.
A correction to Friday’s letter, in the body where it belongs. That edition gave the Michigan preliminary of 47.8 as the benchmark and claimed no final figure because none could be verified before publication. The final, out that morning, was 48.1, and the expectations sub-index was revised to 46.3 from 45.8. The revisions run in the direction of marginally less gloom than first reported. The argument Friday made does not change; the two numbers attached to it do, so they are corrected here.
One caution on the figure this edition leans hardest on. The 4.6% is a survey median of what households say they expect, not a measurement of what anything costs. It is a statement of belief collected by interview, and beliefs and outcomes are different objects. It matters because central bankers treat it as though it were a leading indicator, which makes it consequential whether or not it turns out to be accurate.
Put the two halves of this letter together and the trap is visible. The Federal Reserve is tightening into an energy shock it cannot reach, in an economy whose households already rate conditions at 48.1 and whose sentiment has fallen 15% since January. Higher rates will not reopen the strait. They will, if they work as designed, reduce the demand for everything that is not fuel. Meanwhile the thing that would actually lower the oil price is a diplomatic settlement that was on the table on Saturday and was declined. So the committee meeting on 27 October faces a choice between two bad readings: tolerate 4.6% expected inflation and risk it setting, or tighten into a consumer who is already retreating, in order to offset a price the tightening does not touch. There is no version of that meeting in which monetary policy is the right instrument. There is only a version in which it is the only one the committee controls.
RULES OF ENGAGEMENT
Wednesday measures August
Wednesday is the number, and understand in advance what it can and cannot tell you. August personal consumption expenditures publish on 30 September, and no figure is claimed here. The benchmark is July’s core reading of 3.3%. The critical point is the reference period: this is a measurement of August, a month that ended four weeks before Saturday’s rejection and before this morning’s move in crude. Whatever it prints, it is not a reading on the oil shock. It is the last clean look at where the index stood before it.
The Dallas Fed’s Texas manufacturing survey published at 10:30 Eastern this morning, forty-five minutes before this reaches you, and no September figure is claimed. The August benchmarks, from the bank’s own release of 31 August: general business activity 11.6 against 1.3 in July, production 16.1, new orders 22.0, employment 8.0 against 12.2.
In that release, read the two price lines before the headline. Prices paid for raw materials stood at 44.1 in August, up from 41.3. Prices received for finished goods stood at 22.7, down from 25.6. Manufacturers were already absorbing roughly twice as much input cost as they were passing on, before the weekend. Texas is also the district where an oil move shows up first and in both directions, as a cost to manufacturers and as revenue to the energy sector, so read it knowing it is not a neutral sample.
Treasury auctions thirteen-week and twenty-six-week bills at 11:30 Eastern, after this publishes, so no result is claimed. This is the test flagged on Thursday, when the five-year and seven-year sales both drew weak indirect participation: demand at the front end is the cleanest read on whether that was about duration or about Treasury paper as such.
Tomorrow brings three readings worth having the prior figures for, all of them taken from the economic calendar rather than from primary releases. August job openings, against 7.271 million previously. September consumer confidence from the Conference Board, against 89.4 – a different survey from Michigan’s, weighted more toward the labour market, and the gap between the two has been the argument all month. And the July Case-Shiller house price index, against 2.1% on the year.
Wednesday is also quarter-end, which is its own event in the funding market regardless of anything happening in the Gulf. And the Federal Open Market Committee meets on 27 and 28 October, by which point it will have seen September PCE, the September employment report and whatever the strait has done in between.
The exposure is an inflation shock arriving through a channel monetary policy does not reach, at the exact moment the expectations that justify monetary policy are breaking upward. Brent is above $108 and West Texas above $96 because a settlement was declined on Saturday, not because a barrel went missing. Households told the University of Michigan on Friday that they expect 4.6% inflation over the next year, against 4.0% a month ago, while rating present conditions at 48.1 and cutting their view of their own finances by about a tenth in a single month. The ten-year Treasury is at its highest since July 2007 and the thirty-year at 5.52%, which is the market saying it expects the committee to keep going. Wednesday’s PCE print will not settle any of this, because it measures August. The first official price index that contains this weekend does not exist until the middle of October, eleven days before the committee sits down.
Editorial sources: Reuters via Yahoo Finance, 28 September 2026, 7:23 a.m. Eastern, for Brent crude at $108.48 a barrel at 6:35 a.m. Eastern and West Texas Intermediate at $96.16, both up about 4%, for the President’s remarks that “They made a proposal but I rejected it”, that Iran had “outsmarted themselves” by closing the strait and that “I came along, and we put up the greatest blockade ever in military history”, for the terms of foreign minister Abbas Araghchi’s proposal to reopen the strait and resume nuclear negotiations within seven days in exchange for the withdrawal of military strikes, the lifting of the naval blockade and sanctions and the release of Iranian assets, and for approximately 132 ship passages through the strait between 21 and 27 September against a pre-war norm of approximately 130 daily crossings; Al Jazeera, 28 September 2026, independently for the same proposal terms, for the President’s rejection on Saturday, for 132 transits of the strait from 21 to 27 September and roughly 130 crossings each day before the war, and for the estimate that approximately one-fifth of global oil supplies passed through the strait before the strikes on Iran; Trading Economics, Brent Crude Oil, 28 September 2026, for the recovery from a 2.1% decline in the previous session and for Tehran’s demand that the naval blockade and oil sanctions be lifted as the condition of reopening; Trading Economics, United States Government Bond Yields, 28 September 2026, for the ten-year at around 5.22% and described as its highest since July 2007 on strengthening expectations of further Federal Reserve tightening, the thirty-year at 5.52%, the five-year at 5.05% and the two-year at 4.90%; University of Michigan Surveys of Consumers, final September 2026 release of 25 September 2026 (primary release), for the index of consumer sentiment at 48.1, down 7.0% from 51.7 in August and the lowest in four months and down 15% from January 2026, current economic conditions at 50.9, the index of consumer expectations at 46.3 against a preliminary 45.8, year-ahead inflation expectations at 4.6% against 4.0% and long-run expectations at 3.4% after three consecutive months at 3.3%, and for Joanne Hsu’s statement that views of current and year-ahead expected personal finances both weakened about 10% this month with concerns over high prices continuing to climb; Federal Reserve Bank of Dallas, Texas Manufacturing Outlook Survey for August 2026, released 31 August 2026 (primary release), for general business activity at 11.6 against 1.3 in July, production at 16.1, new orders at 22.0, employment at 8.0 against 12.2, prices paid for raw materials at 44.1 against 41.3 and prices received for finished goods at 22.7 against 25.6; Trading Economics economic calendar for the United States, 28 and 29 September 2026, for the 10:30 Eastern Dallas Fed release, the thirteen-week and twenty-six-week bill auctions at 11:30 Eastern, and the prior readings of 7.271 million job openings, 89.4 on Conference Board consumer confidence and 2.1% on the year for the Case-Shiller house price index; U.S. Bureau of Economic Analysis, Personal Income and Outlays for July 2026, released 26 August 2026, for core personal consumption expenditures at 3.3% and the August release scheduled for 30 September 2026; Federal Reserve Board, FOMC statement of 16 September 2026 (primary release) for the quarter point increase to a target range of 3-3/4 to 4 percent, and the Federal Reserve’s FOMC calendar for the meeting of 27 and 28 October 2026.
END OF TRANSMISSION.
EYES ONLY
EYES ONLY
SUBSCRIBER ONLY // DO NOT FORWARD WITHOUT PERMISSION